Vehicle expenses and who bears them: the field that decides your profit
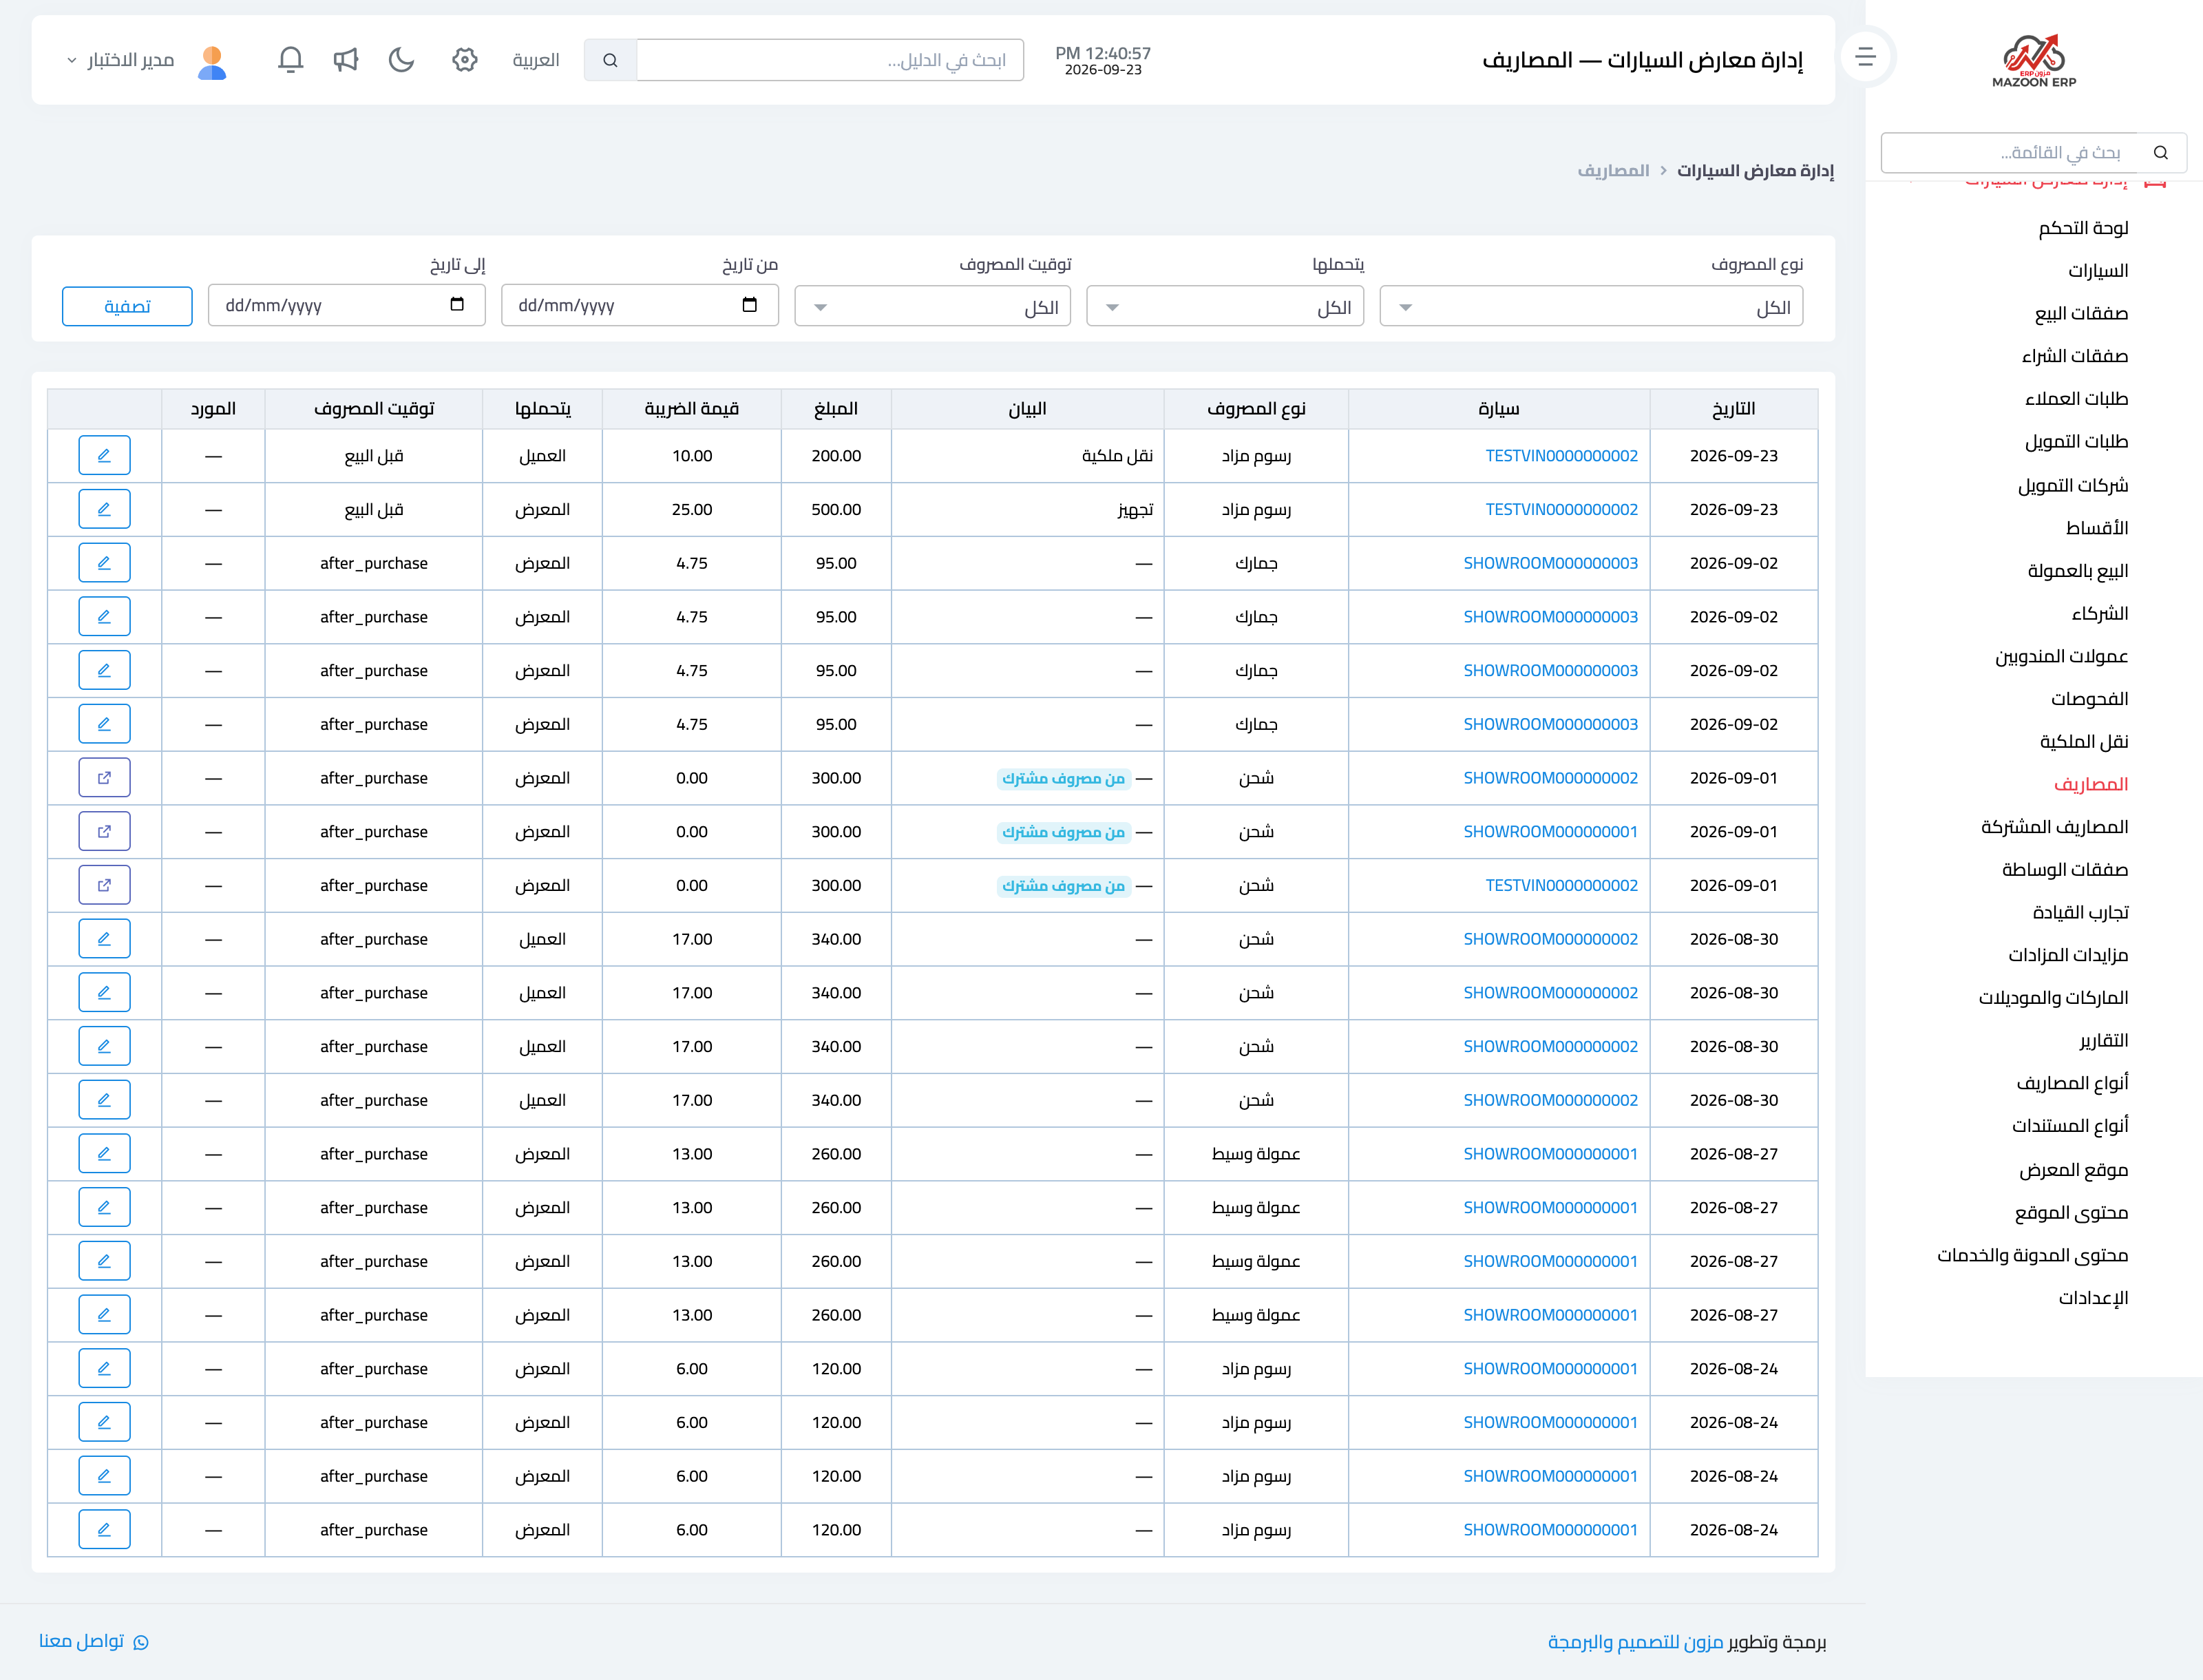
Every expense you record against a vehicle carries a small field called who bears it, with only two values: the showroom or the customer. It is the most consequential field in the module, because the choice changes cost, profit, the invoice and the VAT return all at once.
Image 1 — the vehicle expenses screen.
An expense the showroom bears
Detailing a car before display, say, or fixing a fault found during inspection. Such an expense:
- is added to the vehicle's total cost, reducing your profit on sale;
- has recoverable input VAT on the return, because you are its final consumer.
An expense the customer bears
Transfer fees you pay on the buyer's behalf and then recover from them. Such an expense:
- is not added to the vehicle's cost, because it was never your cost;
- is added automatically as a line on the sales invoice so it is recovered from the buyer;
- has input VAT that is not recoverable — a point many get wrong.
Why is VAT on a customer-borne expense not recoverable?
Because you recover it at its full value including the tax, without charging output VAT on it — it is a disbursement made on someone else's behalf, not a service you sold. Recovering the input VAT as well would mean collecting the tax twice: once from the buyer and once from the tax authority. The system handles this for you, but understanding it helps you classify expenses correctly.
Expense timing
You also record whether the expense occurred before or after the purchase, which is useful for separating acquisition costs from preparation costs.
Attachments
The expense invoice or receipt can be attached directly to the record, up to ten megabytes per file. That is what makes reviewing costs later possible without digging through paperwork.
Screenshots
Try what you just read on your own data
Open a free 7-day trial — no credit card, with your own company link in minutes.